


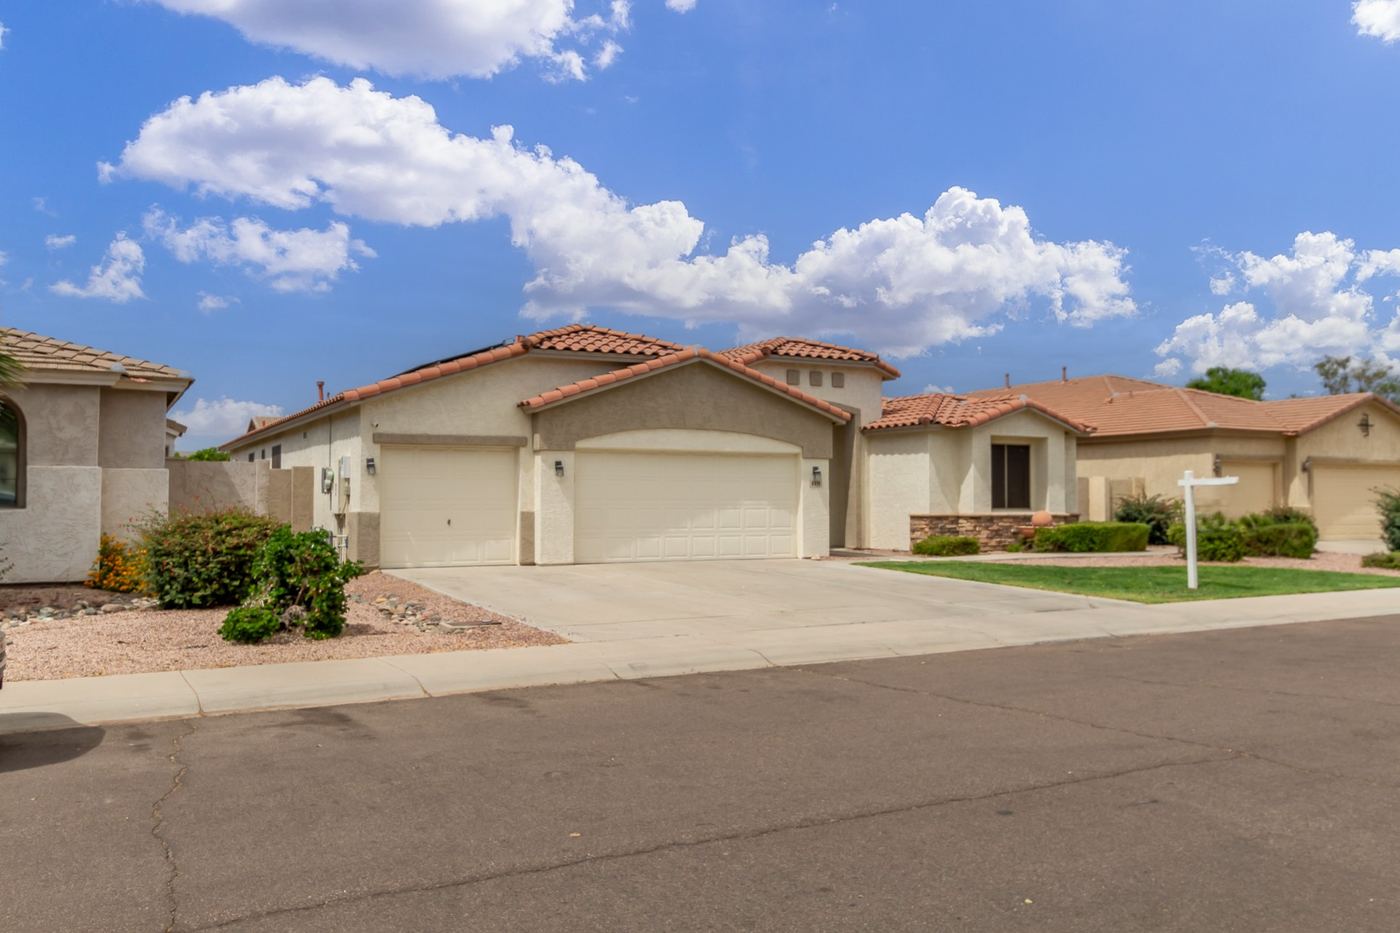
I bought my own home in Goodyear by assuming the seller's FHA loan in October 2023. ABC15 and Business Insider both covered the story. People still ask me about it almost every week, usually with the same question: "Was it worth it?"
My honest answer: on the right house, yes. But the rate is only one part of the story. The other parts are the wait, the paperwork and the gap. Here's what I learned from the buyer's side of the table, and how I use it when I help clients look at homes with assumable FHA or VA loans, subject to lender approval.
What an assumable mortgage is
An assumable mortgage lets a qualified buyer take over the seller's existing loan, including its rate and remaining terms, instead of starting a brand-new loan. FHA and VA loans are often assumable. Conventional loans usually are not. Every assumption is subject to lender approval and the loan's terms, and the servicer has to confirm the loan can be assumed before anyone counts on it.
That's the short version. Living through one taught me the long version.
Lesson 1: The rate was worth it
That part is exactly what you'd hope. Taking over an existing loan meant I didn't have to start fresh at today's rates. For me, on that house, it made the purchase work.
I don't lead with the rate when I talk to buyers, though, because the rate is the easy part to understand. The next three lessons are where buyers get surprised.
Lesson 2: The wait is longer than a normal close
The servicer controls the timeline, and the servicer is not in a hurry. An assumption does not move at the speed of a typical purchase loan. If you plan your lease, your move-out date or the sale of your current home around a normal closing schedule, you can end up squeezed.
What I tell buyers now: build the longer timeline into the contract and into your moving plans from day one. Talk it through with the seller's side early so nobody is surprised halfway through.
Lesson 3: The paperwork is real
People sometimes hear "take over the seller's loan" and picture a simple handoff. It isn't. The servicer approves you much like a lender would, and they will ask for documents.
My advice is simple: have your documents ready before they ask. Every delay in sending paperwork adds time to a process that is already slower than a regular loan.
Lesson 4: The gap is the whole conversation
When you assume a loan, you take over the remaining balance, not the purchase price. The difference between the price and the balance is the gap, and the buyer generally needs a plan to cover it.
This is the biggest reason assumptions do or don't happen. Before I write an offer on an assumable home with a client (every assumption is subject to lender approval), I want to know exactly how the gap will be covered. If that answer isn't clear, the rate doesn't matter yet.
Patience is a strategy
Buyers who expect regular-loan speed get frustrated. Buyers who plan for the wait get the loan they came for. That's really the whole lesson of my own purchase. On the right house, I'd make the same call again.
It's also why I'll tell a client honestly when an assumption doesn't pencil out. Sometimes the gap is too big, the timeline doesn't fit, or the house itself isn't right. An assumable loan, subject to lender approval, doesn't fix a house that's wrong for you.
How I help buyers find assumable homes
Because I've done one myself, I keep track of Arizona homes that may have an assumable FHA or VA loan. If you're curious, these are the first questions I'd want answered on any home:
- Is the loan actually assumable? It has to be confirmed with the servicer, not assumed from the listing, and any assumption is subject to lender approval.
- How big is the gap, and how will it be covered?
- How long is the servicer taking right now? Plan the contract and the move around it.
- On a VA loan, how is the seller's entitlement handled? That matters to the seller and shapes the deal.
Every one of these is subject to lender approval and the loan's terms.
Frequently asked questions
Did Terry Day really assume a mortgage on his own home?
Yes. I assumed the seller's FHA loan when I bought my home in Goodyear in October 2023, and ABC15 and Business Insider covered the story.
How long does a mortgage assumption take?
Longer than a typical purchase loan. The servicer controls the timeline, so I build extra time into the contract and the move-out plan.
What is the gap on an assumable mortgage?
It's the difference between the purchase price and the remaining loan balance. The buyer generally needs a plan to cover it before writing an offer, and the assumption itself is subject to lender approval.
Are FHA and VA loans assumable?
They often are, but each loan has to be confirmed with the servicer, and any assumption is subject to lender approval and the loan's terms.
Let's talk
If you're buying in Phoenix, Scottsdale or anywhere in the Valley and want to know whether a home may come with an assumable FHA or VA loan, call or text me at 602-483-4665. I'll tell you honestly whether it pencils out. Assumptions are subject to lender approval and loan terms.
Terry Day, DeLex Realty